On 1 June 2026, the OECD published a consultation report suggesting amendments to Chapter VII of their guidelines, which addresses transfer pricing aspects of intra-group services. Comments could be submitted in writing by tax specialists and the professional community until 22 July 2026, and a public hearing has been planned for the end of 2026. The discussion draft does not, at this stage, represent OECD's consensus view and therefore cannot be referred to directly yet. However, it points the way forward and offers a useful framework for assessing existing models.
The proposed amendments to the OECD Guidelines cover a wide range of services, from managerial and administrative support to manufacturing, sales, R&D or technical services. The OECD explicitly states that the aim is not to change the general principles of transfer pricing, but to modernize the existing guidance, align it with Chapters I to III of the OECD Guidelines and show its practical application on 21 new examples. The proposal is not intended to change the basic principles of the original wording of Chapter VII, but specifies it and provides more detailed instructions on how intra-group services should be characterized, documented and priced.
Intra-group services have long been among the most frequently reviewed areas of transfer pricing in the Czech Republic. The tax administration focuses its scrutiny primarily on the management and support administrative services, while companies receiving such services from foreign headquarters commonly encounter extensive requirements during tax audits to prove that the services were actually provided and brought a specific benefit to the Czech service recipient.
For Czech taxpayers, the OECD proposal brings a double message. It confirms the importance of proving the actual performance and the expected benefit, which are well known from Czech tax audits. At the same time, it may help to refine some simplistic approaches and generic assumptions of the Czech tax authorities and help prevent situations where the existence of a service would be denied solely because the tax administrator does not consider the contemporaneous evidence provided to be sufficient to substantiate the full value of the service.
TP analysis begins with the accurate delineation of the transaction
The most visible shift in the proposed new wording is the emphasis on the accurate delineation of the transaction within the meaning of Chapters I to III of the OECD Guidelines. The definition of a service, for example, as a “management fee” or an “IT service” should not in itself determine the economic content of the performance or the correct transfer pricing method. The commercial and financial relations between the companies involved, the functions actually performed and the risks borne, as well as economically significant circumstances, should be decisive in this regard.
The functional analysis should capture not only the economic functions of the service provider, but also the activities and responsibilities of the service recipient as well as other members of the group. In particular, decision-making authority, risk control, allocation of assets, interdependencies and links to other transactions may be relevant. Particular attention should be paid to services linked to intangible assets, such as granting of access to technology, data or significant know-how. In such cases, it may not be appropriate to price the service using the cost-based method. In some cases, it may even be more correct to include the value of such a service in the pricing of another transaction.
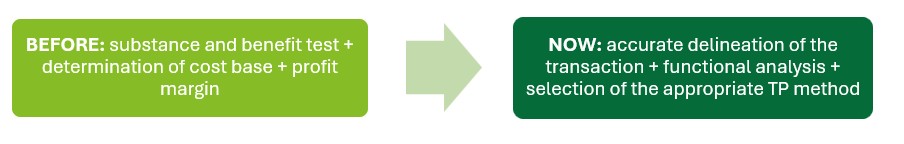
In practice, it is therefore appropriate to start the transfer pricing analysis of a given service with the question “What is really going on between the parties?”, not with the question “What are the costs of the provider?”, which is often the starting point in practice today. Only after a precise delineation of the transaction it can be assessed whether a one-sided method is appropriate and which of the parties should be the tested party.
The consultation proposal thus indicates a significant shift in the general approach to intra-group services:
Economic substance and benefit test
The accurate delineation of the transaction goes hand in hand with the assessment of whether the activity of one member of the group brings economic or commercial value to another member and whether an independent party would be willing to pay for a similar service (the so-called benefit test). In this part, the proposal emphasizes that the mere fact that a similar service does not normally occur between independent companies should not be sufficient to reject an intra-group transaction. The OECD Guidelines, as with other types of intra-group transactions, admit that groups of companies have the possibility and incentive to provide services to each other that independent companies would not usually take part in – e.g. because of excessive fragmentation of activities or because of the preservation of trade secrets.
We consider the following to be the three most relevant areas related to the substance and benefit test in the Czech environment, in which the differences between the view of taxpayers and the tax administrator most often arise:
- Time aspect: The consultation proposal emphasizes that the benefit may arise (or may be reasonably expected) in the period in which the activity was performed, but also later in the future. In some cases, it may be necessary to evaluate data over several years in order to assess whether the benefit could be reasonably expected at the time of the activity. In contrast, in Czech practice, companies often encounter that the tax administrator wants to prove the contribution to the economic activity of the recipient of services particularly in the year for which the audit has been carried out.
- Shareholders activities: The consultation proposal defines in more detail the so-called “shareholder activities”, i.e. activities performed by a company in its capacity as a shareholder solely as a result of its ownership interest, if those activities do not provide any benefit to the subsidiary. The proposal now provides specific examples of such activities – e.g. management and acquisition of ownership interests, statutory reporting of the parent company or activities related to the fulfilment of its own tax obligations (unless other economic benefits can be identified).
- Duplication: Already in the original wording, the OECD Guidelines specified that an intra-group service does not normally arise if the activity of one group member merely duplicates an activity that another group member performs for itself or that is already performed for it by another group member or a third party. However, the proposal now clarifies and provides examples of situations to which duplication does not apply. For example, temporary duplication of services in the reorganisation of proceedings, obtaining a second legal opinion to reduce the risk of an incorrect business decision, complementary activities or concurrence of activities required by law may be economically justified.
The existence of a service and its price are two different issues
One of the most important clarifications of the consultation proposal from the point of view of Czech practice is a clear separation of the benefit test from the determination of the arm’s length price. The assessment of whether a service meets the benefit test should not depend on the amount that the recipient is willing to pay for it. Therefore, a price discrepancy should not automatically lead to the denial of the existence of the service.
These conclusions are very relevant for the Czech environment, where it is often unclear when the assessment of intercompany services should be carried out under Section 24(1) of the Income Tax Act – general tax deductibility of expenses; or under Section 23(7) – transfer pricing. According to the tax law, the taxpayer must first be prepared to bear the burden of proof regarding the tax deductibility of costs, i.e. to document the substance and its connection with the achievement, securing and maintenance of taxable income. Only when there is sufficient proof of the actual provision of services does the assessment usually move to the transfer pricing matters, while in practice the exact moment of such a transition is not clearly defined by the tax law and may be subject to disputes.
The new wording of the OECD Guidelines corresponds to the conclusions of SAC Decision No. 2 Afs 27/2023-41, according to which, in the context of the assessment of the general tax deductibility of costs, the very existence and benefit of the service received cannot be questioned solely because of doubts about the character and amount of the agreed remuneration. The tax administrator should “only” test the obvious (un)reasonableness of the cost as part of general deductibility. However, the assessment of the arm’s length price should be performed separately in the transfer pricing regime.
It is noted that this should work equally in opposite direction: even a thorough documentation of the benefit does not in itself confirm the correctness of the price.
The cost-plus is not an automatic method
The proposal rejects the assumption that an intra-group service should be primarily priced using a cost-based method (cost plus or TNMM). As mentioned above, the selection of method should only follow the accurate delineation of the transaction and should take into account the perspective of both the provider and the beneficiary and their realistically available alternatives. The proposal also stresses that the service provider should not automatically be considered as a tested party.
For strategic, knowledge-intensive or highly integrated services, it may be more appropriate to use a different method. Where information on highly-comparable independent services is available, the CUP method may be more appropriate. Where both parties contribute unique and valuable intangibles, their operations are strongly interlinked or they jointly carry significant economic risks, the profit split method may be more appropriate.
The provider’s costs remain relevant in the price assessment, but do not have to determine the value of the service. High internal costs do not in themselves justify a price exceeding the amount that the recipient would pay for a comparable external service. Conversely, a cheaper local offer may not be truly comparable if the group service provides a different scope, quality, security, integration or know-how protection.
The extended rules also deal with the so-called pass-through costs, i.e. costs recharged by the service provider without a mark-up. The profit mark-up should relate primarily to the company’s own activities, not to the reimbursement of external costs without adding its own additional value. When assessing what costs to recharge without or with a mark-up, industry standards and market practice should also be taken into account, which is modelled on the example of a marketing agency that does not recharge the client for the costs of the purchased advertising space.
Documentation: from retrospective description to contemporaneous evidence
The proposal supplements the general transfer pricing documentation requirements set out in Chapter V of the OECD Guidelines by providing specific guidance for intra-group services. This is not a mandatory minimum list of evidence, but rather examples of possible means of proof. However, the emphasis is clearly placed on the contemporaneous collection of evidence.
This corresponds to the long-term Czech practice, in which companies in tax audits are routinely asked to provide proofs of actual service delivery, such as e-mails, outputs, minutes, project materials or timesheets. However, the perspective of foreign headquarters may be different and they may perceive such requirements as a local administrative formalism. The consultation proposal gives Czech companies additional substantiation as to why it is appropriate to create and store evidence on an ongoing basis and can therefore help them communicate Czech requirements to the group.
The simplified regime for low value-adding services remains broadly unchanged in the consultation paper. It continues to envisage a uniform five percent cost plus mark-up without the need to substantiate it with a benchmark study, provided that the underlying conditions for the use of this regime are met. (Note: the Czech methodological guideline of the General Financial Directorate D-10 defines a mark-up of two to seven percent). At the same time, the proposal emphasizes that the mark-up accepted in this way is a tool of administrative simplification, not a reference benchmark for other types of services, such as services with higher added value.
What Czech companies should do now
The question remains what practical impact the OECD consultation proposal may have on Czech companies and how they should respond to it. As mentioned above, the update of Chapter VII represents an evolution rather than a revolution. More detailed guidance can help reduce ambiguity and disputes, but at the same time it can provide tax administrators with new arguments when reviewing intra-group services. We would therefore recommend the following steps to all Czech entities that pay or charge for any type of intra-group service:
- Assess whether the cost-based method remains the most appropriate transfer pricing method, in particular for services requiring a higher level of professional know-how or greater involvement of strategic or decision-making powers.
- Examine the cost basis of management services and identify and exclude shareholder’s costs as defined in the proposal.
- Consider splitting the general category of ‘managerial services’ into more specific categories to allow for a more precise delineation, for example:
- Group treasury,
- Supply chain optimization,
- Support in the implementation of the ERP system; and others.
- Identify low value-adding services and consider the possibility of using a simplified regime.
- Consider recharging costs without a mark-up if the service provider does not add its own functional value to the performance. Consider industry standards and market practice when assessing whether certain costs are to be considered flow-through.
- Set up an internal system of collecting and storing contemporaneous evidence instead of retrospectively compiling descriptive transfer pricing documentation.
In conclusion, the consultation proposal may not be considered a blank cheque for either taxpayers or tax administrators. It places greater emphasis on the economic substance and evidence of intercompany services, while supporting an accurate delineation of the transaction, followed by an rigorous assessment of the transfer price. For Czech companies, it can therefore represent a more precise framework for defending service costs in tax audits, particularly in case of less standard intra-group arrangements.